Home appraisal
The BrokerFold Team — Product + Engineering
Last reviewed
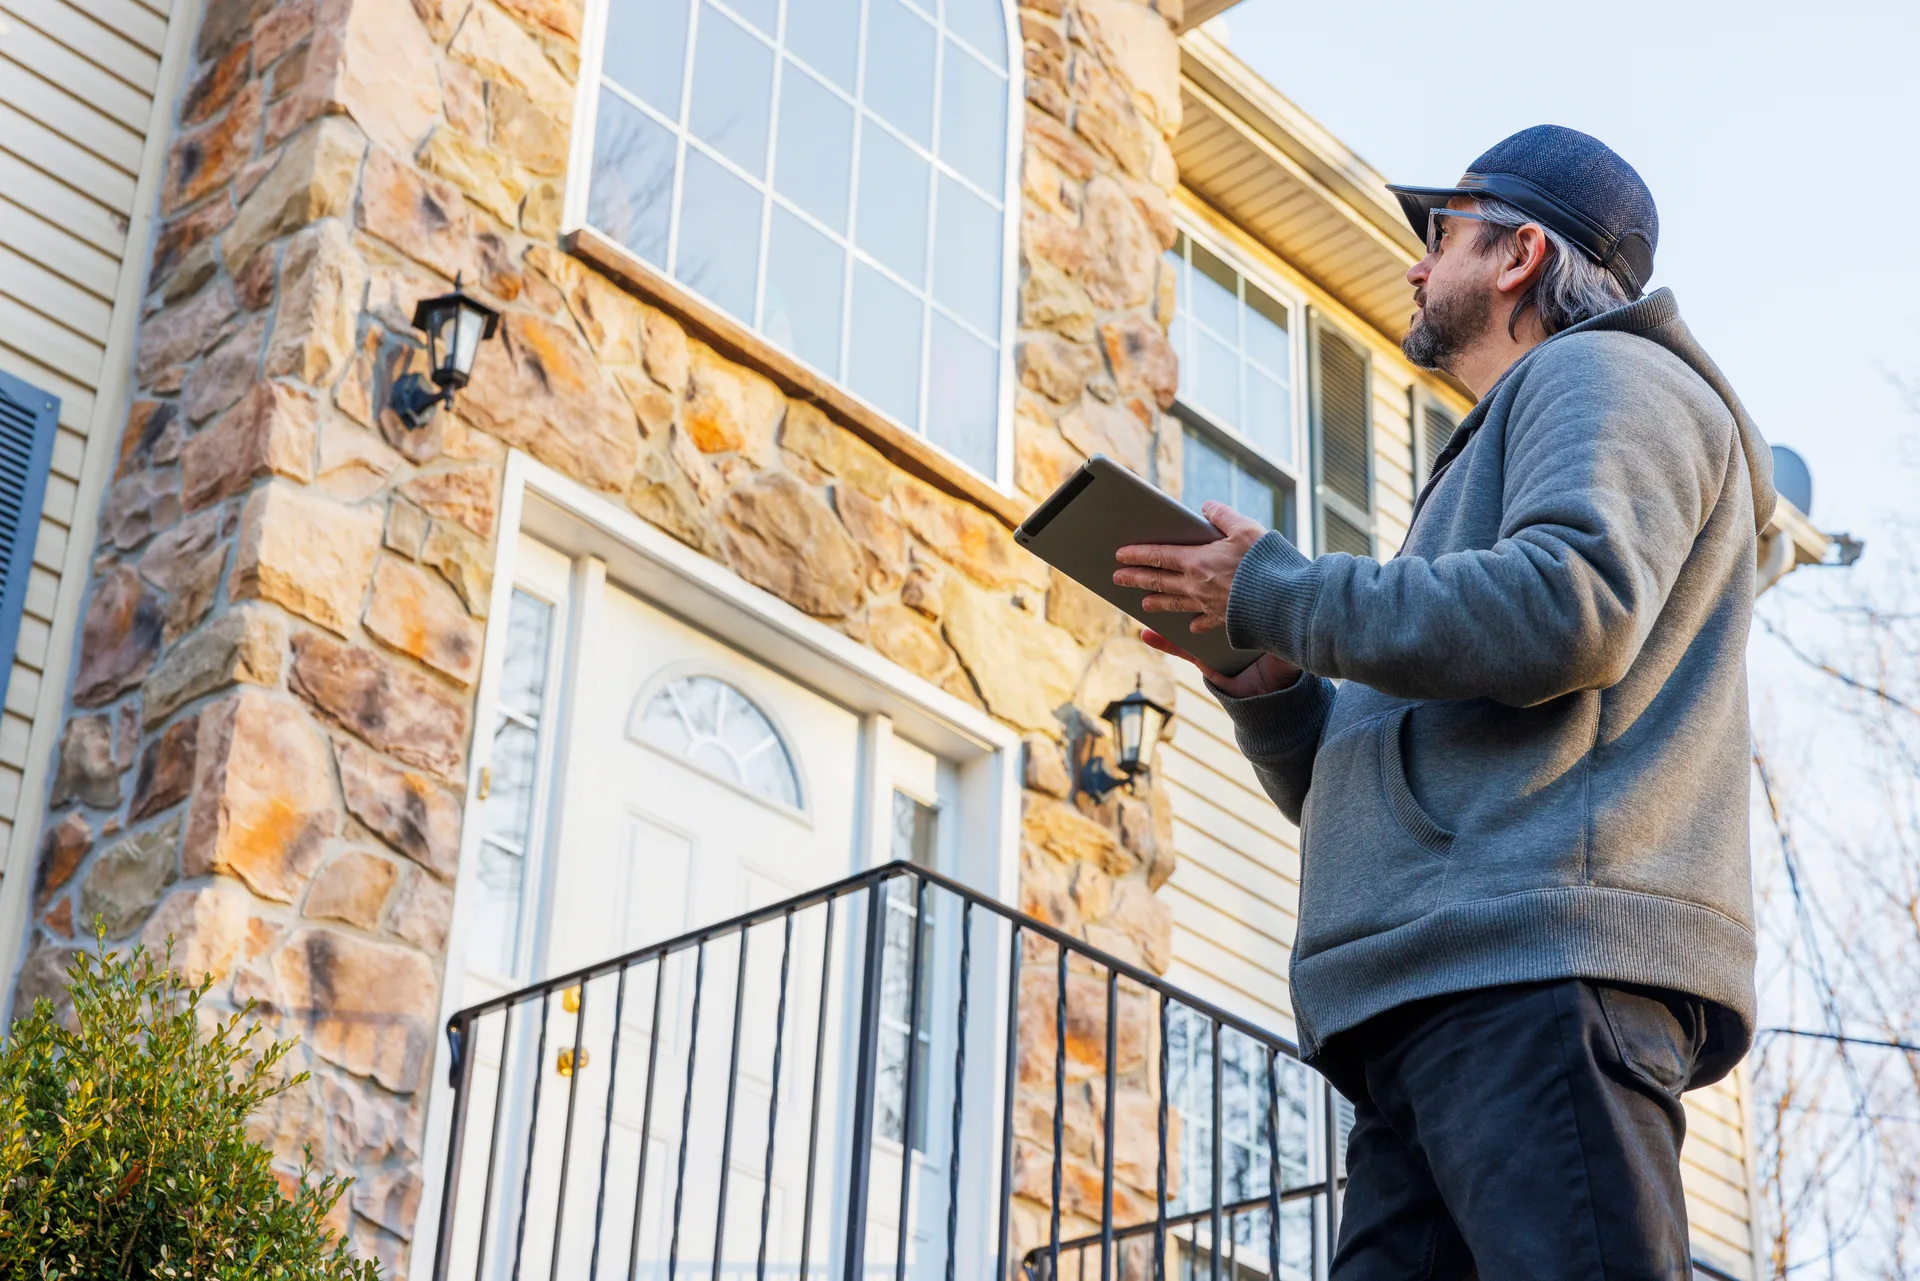
A home appraisal is a formal, independent opinion of a property’s market value prepared by a licensed appraiser — almost always because a lender requires it before advancing a mortgage. The appraiser inspects the property, selects comparable sales, adjusts for differences, and delivers a value the lender uses to size the loan.
Appraisal, CMA, AVM — three different animals
A comparative market analysis is an agent’s pricing opinion, built for listing strategy; an automated valuation model is an algorithm’s estimate, built from data at scale; an appraisal is a regulated professional’s opinion, built for a lender’s risk decision. They often agree; when they don’t, remember whose question each answers. The appraisal is the only one of the three with a veto over your financing, and none of the three is the assessed value your property-tax bill uses.
When the number bites
Low appraisals cluster exactly where buyers most fear them: fast- rising markets where comparable sales lag the bidding, unique properties with thin comparables, and private sales priced on hope. The protections are boring and effective — a financing condition, a realistic bid grounded in actual comparables, and cash reserves if you’re choosing to compete firm. Sellers meet the appraisal too: a deal that dies at financing over value was mispriced somewhere, and relisting data shows it.
Why it matters for your practice
“The bank’s appraisal came in low — now what?” is a panicked call every busy agent eventually gets. A calm explainer on your site, written before anyone needed it, is both the answer and the demonstration that you understood the machinery all along.
Frequently asked questions
What happens if the appraisal comes in below my purchase price?
The lender lends against the lower of price and appraised value, so the gap becomes yours to cover: more down payment, renegotiation with the seller, or — if you wisely kept a financing condition — a lawful exit. This is the concrete risk inside firm offers in hot markets: you owe the price you bid, whatever the appraiser later says.
Is the appraisal the same as the home inspection?
No. The appraiser works for the lender and answers one question — what is this property worth as security. The inspector works for you and answers a different one — what condition is it in. An appraisal noting the roof exists is not an opinion that the roof is sound.
Keep reading
- CMA A CMA (comparative market analysis) is an agent's pricing estimate built from comparable sold homes — the professional answer to what a home is worth.
- AVM An AVM (automated valuation model) prices homes with data instead of a visit. How the models work, where they break, and what they're good for.
- Assessed value vs market value Why MPAC and BC Assessment numbers rarely match what a home sells for — what assessed value is for, and what to use when pricing instead.